P2P Lending Software Development Services
Off-the-shelf lending software forces your business to fit the tool. We build Custom P2P platforms that fit your lending model, your risk rules, your investors & your growth plan.
Full-Cycle P2P Lending Platform Development Services
A P2P platform runs two trust systems at once, borrower trust and investor trust, each with its own risk logic, disclosures and failure points. Treat them as one engine, and one side of your marketplace ends up paying for it. We build both sides as one system for you: web platform, mobile experience and back-office tooling together.
We’ve shipped microfinance platforms, KYC/AML and risk-scoring engines and borrowing-base validation systems for regulated lenders. Our track record in lending software development services backs this. Whatever your model – consumer, SME, invoice, auto, student or specialty peer-to-peer (P2P) lending, we adapt the risk logic and disclosures to fit, without rebuilding your platform underneath.
AI creates tangible impact when it solves a specific problem. We extract and validate financials with document intelligence, price risk with credit scoring, catch fraud at onboarding and transaction level, and match investors to borrowers based on your risk appetite and return targets.
We engineer compliance into the architecture, so you get KYC/AML workflows, audit trails, data residency and regulatory reporting. Fair-lending and investor-protection safeguards come standard too, backed by our delivery experience across nine jurisdictions.
Your existing systems stay exactly where they are. We connect to your LOS, LMS, core banking, payment rails and credit bureaus and modernize what’s already live. With our P2P lending software development, you keep full control of your code, your underwriting logic and your data.
P2P Lending Software Development Services
As a P2P lending platform development company, our services take you from strategy to a compliant, revenue-ready platform, engineered to scale in any market you enter. Our lending expertise also extends to specialized areas such as mortgage lending software.
P2P Lending Consulting & Advisory
- Platform and workflow audits to identify what to keep, fix or replace
- Build vs. buy analysis weighed against your compliance obligations and growth targets
- Architecture reviews spanning both sides of your marketplace, borrower onboarding and investor management
- Risk and regulatory gap assessments specific to your lending model and market
P2P Lending Platform Development
- Custom-built platforms that cover borrower onboarding, investor management, loan matching and disbursement
- White-label lending software you can brand and launch under your own name
- Configurable workflows matched to your credit policy, risk appetite and investor terms
- API-based integrations with payment rails, credit bureaus and core banking systems
P2P Lending Mobile App Development
- Native and cross-platform apps built separately for borrower and investor journeys
- Real-time loan status, repayment tracking and portfolio visibility in-app
- Secure in-app KYC, document upload and eSignature flows
- Push notifications for repayment reminders, funding updates and investor alerts
Financial Document Intelligence & Credit Risk Decisioning
- OCR and LLM-based extraction and validation of borrower financials
- Credit scoring models for risk-based pricing and approval decisions
- Policy rules engines that give your team configurable control without losing audit traceability
- Fraud detection built into onboarding and underwriting
KYC, AML and Regulatory Workflow Implementation
- Identity verification, sanctions screening and AML checks built into onboarding
- Fair-lending and investor-protection workflows aligned to your operating market
- Audit trails, data residency controls and regulator-ready reporting
- Consent, disclosure and eSign workflows that hold up under compliance review
Collections and Recovery Automation
- Segmentation logic that separates self-cure borrowers from high-risk accounts
- Omnichannel, compliant outreach across SMS, email and voice
- Payment plan and settlement workflows with real-time status tracking
- Recovery and legal handoff tracking that feeds data back into underwriting
Legacy P2P Lending Software Modernization
- Incremental re-architecture instead of a high-risk rip-and-replace
- Data migration that preserves loan history and investor records
- Modern API layers wrapped around core systems you're not ready to retire
- Phased rollout plans that keep active loans and investor commitments moving
P2P Loan Servicing, Repayment & Collection
- Amortization schedules, payment application and fee management
- Payment rail integration for ACH, cards and direct debit, with automated reconciliation
- Borrower and investor portals for statements, self-service and repayment history
- General ledger integration for accruals, postings and revenue recognition
P2P Lending Marketplace Development
- Loan listing and bidding engines that match investor capital to borrower demand automatically
- Auto-invest and allocation rules that let investors set criteria once and fund continuously
- Funding pool management for partial funding, syndication and multi-investor loans
- Secondary market infrastructure for investors to trade or exit positions without platform downtime
P2P Lending API Development
- RESTful and event-driven APIs that expose onboarding, decisioning and servicing as reusable services
- Embedded lending APIs that let partners and platforms originate loans inside their own products
- Developer portals, sandbox environments and versioned documentation for third-party integration
- Webhook infrastructure for real-time status updates across loan, payment and investor events
P2P Lending Software Solutions, Built to Plug In and Scale
Every module in our p2p lending software development comes from systems we've already built and shipped for regulated lenders. Our FinTech software development expertise brings that same engineering depth across lending and other financial workflows. When you partner with us, your budget and timeline go toward a lending platform that works, not someone's first attempt at building it.
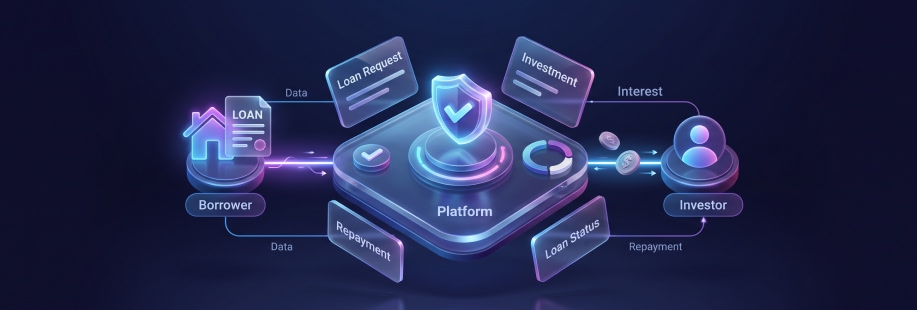
Origination, servicing and reporting shouldn’t live in three disparate systems that don’t agree with each other. We close that gap with one system: configurable product rules, automated repayment scheduling and real-time dashboards, all running on a single source of truth. When decision-makers ask for a number, they get an accurate one, on-demand!
- Centralized Loan Lifecycle Tracking to manage every loan from funding to payoff, in one system
- Automated Repayment Scheduling to calculate amortization, interest and fees without manual recalculation
- Configurable Loan Product Rules to launch new lending products without engineering rework
- Real-Time Reporting Dashboards to give leadership live visibility into portfolio health and loan status
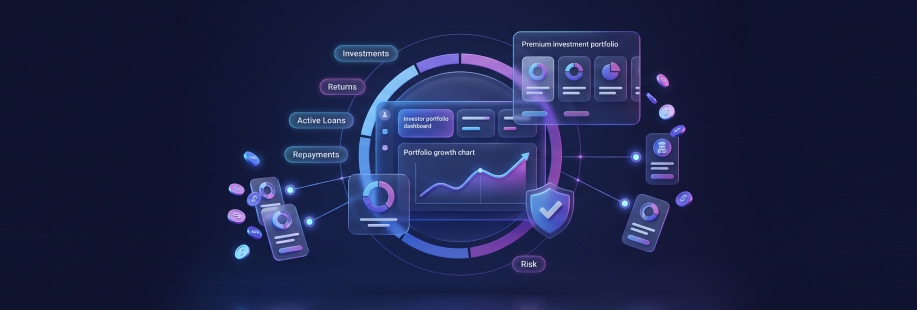
Investors don’t leave loudly; they just stop reinvesting, and capital moves to platforms that show them more. Every unanswered question about a return, every statement that arrives a week late, chips away at investor confidence. We rebuild that confidence with real-time returns, automated statements and portfolio tools built to keep investors watching their numbers grow, not shopping for a better view.
- Automated Portfolio Valuation to calculate real-time returns across every investor’s holdings
- Diversification and Allocation Tools to help investors spread risk across loan grades automatically
- Investor Statements and Tax Reporting to generate compliant documents without manual drafting
- Secondary Market Support to let investors trade or exit positions without platform downtime
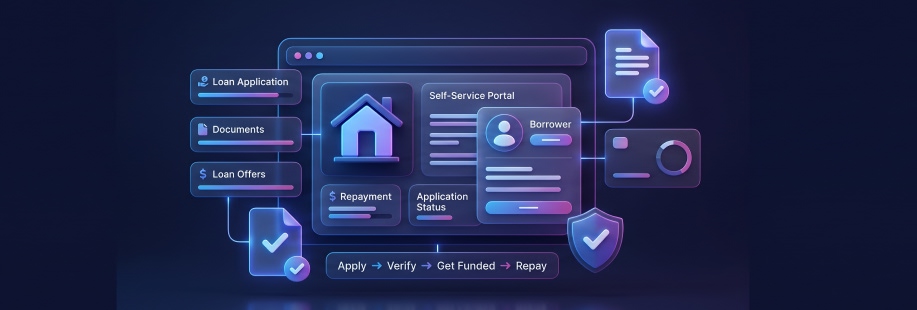
Picture a borrower halfway through an application at 11pm. They hit a question, there’s no one to ask, and by morning they’ve restarted the same application on a competitor’s site. Most platforms fix this with a support line, one more thing borrowers wait on. We fix it with self-serve tracking, document tools and in-app answers built into the application itself, so borrowers never have to wait for your office hours to finish theirs.
- Self-Serve Application Tracking to show borrowers real-time status without a support ticket
- Document Upload and eSignature to move applications forward without printing, scanning or emailing
- Repayment and Autopay Management to let borrowers manage payments without calling in
- In-App Messaging to resolve borrower questions without a phone queue
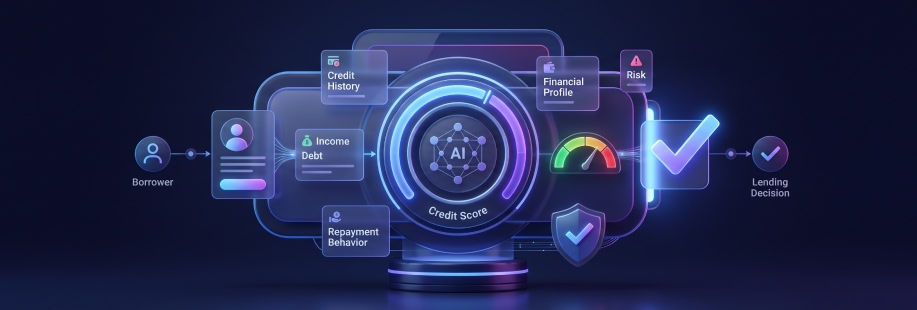
Tighter credit models are supposed to mean lower risk but in reality, static models reject good borrowers and approve some who default months later. This happens because bureau data alone doesn’t show how someone actually manages money.
We’ve built underwriting engines for regulated lenders that read alternative data and real-time signals, and cut default rates in production. Chief Credit Officers get both here, faster approvals and earlier risk detection, without trading one for the other.
- Alternative Data Credit Scoring to assess creditworthiness beyond traditional bureau data
- Configurable Underwriting Rules to give risk teams policy control without waiting on engineering
- Explainable AI Decisioning to document every approval and decline with a clear audit trail
- Dynamic Risk-Based Pricing to set rates that match real borrower risk instead of flat tiers
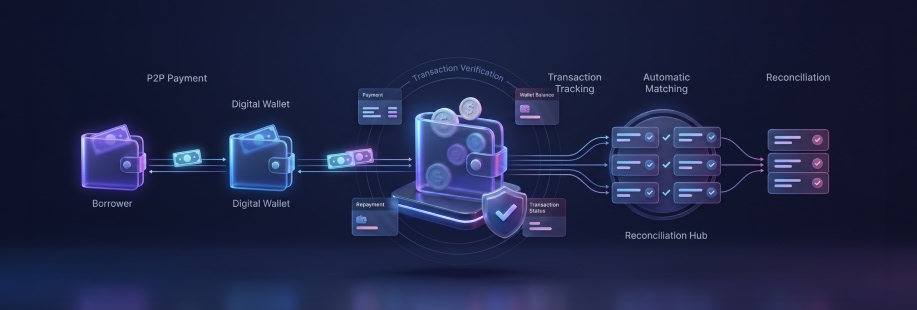
Finance teams on manual platforms lose a significant chunk of their productive time every month matching transactions across payment gateways, payouts and repayments before the books close. The problem isn’t the accounting but the system underneath forcing your team to reconcile manually.
We build the payment and reconciliation layer that bridges the gap with multi-rail processing, automated disbursement and real-time matching that reconcile every transaction against your ledger in real-time. Your finance team stays productive and your books close on schedule instead of on overtime.
- Multi-Rail Payment Processing to support ACH, cards, wires and direct debit from one system
- Automated Disbursement and Payout Engine to route funds to borrowers and investors without manual approval steps
- Digital Wallet Infrastructure to hold, transfer and settle funds within your platform
- Real-Time Reconciliation to match every transaction against your ledger automatically
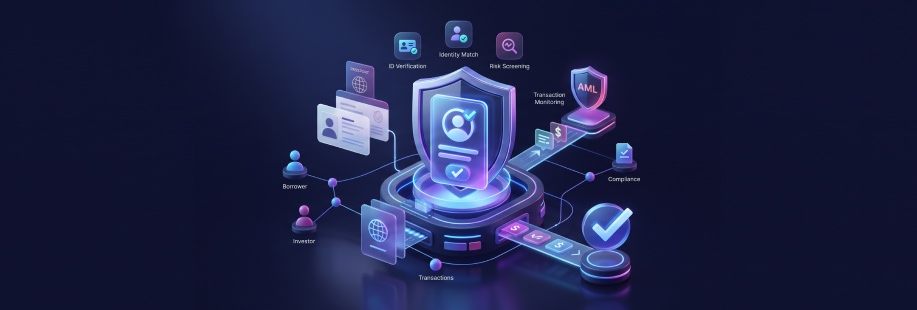
One missed sanctions match is all it takes to turn a routine audit into a suspended license. Manual identity checks and disconnected AML screening rarely give any warning before they fail. They fail quietly, and a regulator ends up finding what your team didn’t. We build the system that catches it first. Automated verification and screening flag risk at onboarding, before a file ever reaches approval, so your compliance team spends its time on real cases, not damage control.
- Automated Identity Verification to confirm borrower and investor identity without manual document review
- Sanctions and Watchlist Screening to flag high-risk individuals before onboarding completes
- Ongoing Transaction Monitoring to detect suspicious activity after onboarding, not just at signup
- Audit-Ready Compliance Reporting to generate regulator-ready documentation on demand
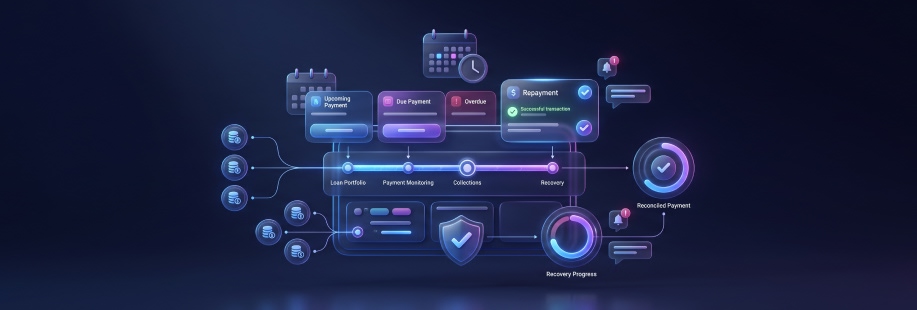
Most collections platforms send the same reminder email to a borrower five days late and one ninety days gone. That’s how recoverable accounts turn into write-offs. Some accounts deserve a second look before you write them off. We build the engine that gives every account that look. Risk scoring separates self-cure borrowers from high-risk ones, automatically. Compliant outreach responds to each differently. It’s the same collections architecture we’ve built for regulated lenders modernizing recovery at scale. The accounts still worth saving get treated like it, before the write-off!
- Risk-Based Segmentation to separate self-cure borrowers from high-risk accounts automatically
- Automated Compliant Outreach to run SMS, email and voice campaigns within legal communication limits
- Payment Plan and Settlement Workflows to offer structured repayment without manual negotiation
- Recovery and Legal Handoff Tracking to keep visibility on accounts even after they leave your team
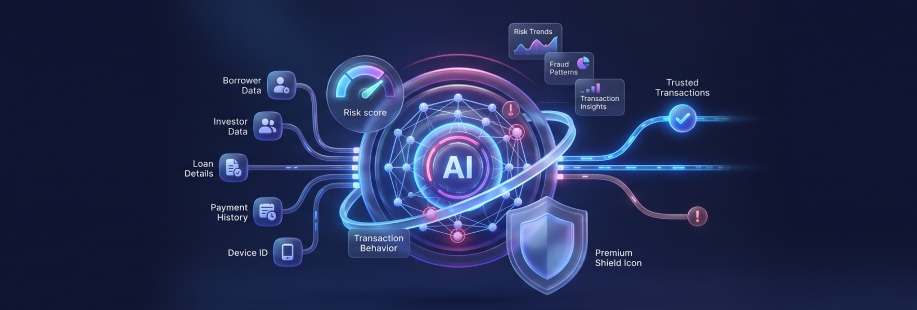
By the time a static rule engine flags fraud, the money’s usually already moved. Rule-based systems catch yesterday’s patterns. Fraud doesn’t wait around for rules to catch up. We build detection on behavioral baselines instead of fixed thresholds. The model learns each borrower’s and investor’s normal transaction pattern, then flags statistical deviation from it, not a hardcoded number. Anomalies get scored and routed in real time, before settlement, not queued for a fraud analyst to find in next week’s report.
- Real-Time Fraud Detection to flag suspicious applications and transactions as they happen
- Behavioral Anomaly Monitoring to catch patterns static rules miss
- Portfolio Risk Analytics to track exposure, concentration and vintage performance in one view
- Automated Alerting and Case Management to route flagged activity to the right team instantly
Proven Lending Engineering, Applied to P2P Lending App Development
We've already delivered borrower onboarding, credit decisioning and fraud detection engineering for regulated lenders; that same engineering now powers the P2P and marketplace platforms we build.
Microfinance Lending Engineering
Fraud & Risk Management
AI-based Fraud Detection & Prevention Software
Asset-Based Lending Engineering
Legacy Asset-Based Lending System Modernization
Build custom P2P lending software engineered to win the borrower before a competitor can
Why Lenders Choose Us as Their P2P Lending Software Development Company
Domain expertise first, code second. We bring practice-proven expertise in designing and taking P2P lending platforms live with the compliance rigor and risk discipline our teams have already proven on regulated lending systems.
Domain-first lending engineering
We understand the operational logic behind lending workflows: borrower onboarding, credit decisioning, ABL validation, servicing, collections, regulatory reporting.
Compliance by design
Audit trails, access controls, data residency, retention policies and regulatory reporting get built into the architecture, not added after launch.
Intelligence layered into lending workflows
OCR, LLM-assisted extraction, risk analytics and workflow automation go where they cut manual effort and sharpen decision visibility.
Modernization without unnecessary replacement
We extend existing LOS, LMS, core banking and servicing systems through APIs and phased migration, no disruptive rip-and-replace required.
Build, Optimize and Scale with Lending Technology
Explore practical insights, proven use cases, and real client results across mortgage, lending and financial services software.


Your Custom P2P Lending Software Questions, Answered
What do your P2P lending platform development services include?
Our P2P lending software development services cover the full stack. We onboard borrowers and investors, run KYC/AML checks, make credit decisions, match loans in the marketplace, and process payments and wallets. We also help you manage servicing and collections and generate the compliance reports regulators expect. Custom platforms can also include admin dashboards to track risk, portfolio performance and audits. Your lending model, target markets and compliance requirements shape the exact scope every time.
Can custom P2P software integrate with our existing LOS, LMS, or core banking system?
Yes. A custom P2P lending setup can connect to your LOS, LMS, or core banking using REST or GraphQL APIs. It can also use message based middleware so updates move as events happen. That way, the new P2P service exchanges data with your existing tools while keeping your core setup in place. It also supports identity checks, payment matching, and role based permissions. This helps ops, risk, and compliance teams use the same shared records from a single source of truth.
Can you modernize our existing P2P or lending platform without disrupting live loans?
Yes. You can modernize a live P2P or lending platform without disrupting live loans by wrapping existing systems in modern APIs and microservices. New services connect through updated APIs. Smaller components can be upgraded first, such as onboarding, loan setup, servicing, or the investor view. The key is to let the old setup and the new setup work side by side for a while. Active loans keep moving because the switch is gradual, not a hard transition. Data stays aligned during the change. That way, current loan records and investor commitments continue uninterrupted without losing updates.
What kind of post-launch support and maintenance do your p2p lending app development services offer?
After the launch, we keep supporting the P2P lending platform. We follow an SLA that sets clear response and fix times. We also run ongoing managed work, like system checks, patching, backup runs, and performance tuning. Along the way, our team helps you improve the product, add new capabilities, keep up with regulatory changes, and refine AI parts. We also watch for compliance updates as lending rules change in the US, the UK, and the EU.
How do you implement credit scoring and underwriting workflows for P2P?
We combine bureau data, alternative data, rules engines and machine learning models to score credit risk and price loans accurately. We program your lending policies into configurable workflows and route edge cases to senior underwriters automatically. We also make every decision to be explainable, so your approvals and declines hold up under compliance review and investor due diligence.
Can the platform support third-party credit bureaus and alternative data for P2P?
Yes, P2P lending platforms can integrate with major credit bureaus and alternative data providers across the US, UK and EU, alongside identity verification, income verification and bank-statement analysis services. The architecture is built to add or swap data providers as your underwriting strategy or target markets evolve.
What AI capabilities can be added to a P2P lending platform?
We apply each capability where it cuts manual effort or improves decision accuracy. Feature enhancements can include document processing and OCR, AI-assisted credit scoring and underwriting support, fraud and anomaly detection, collections prioritization and borrower or investor chat assistants for status checks and document requests.
How do you secure P2P lending platforms and investor data?
We secure your platform with end-to-end encryption, secure API gateways, role-based access control, tenant isolation and audit logs. Our team runs continuous vulnerability scanning, maintains solid backups and builds disaster recovery into the system. We tailor the entire security framework to your data sensitivity, deployment model, regulatory environment and third-party risk profile.